Asset Protection in Bankruptcy
Asset Protection in Bankruptcy: How to Keep Your Property in Oregon
Filing for bankruptcy carries a lot of emotional weight, but much of the anxiety stems from a persistent myth: the idea that filing means handing over everything you own. In reality, bankruptcy laws exist to offer honest debtors a clean financial start, not to strip them of their basic standard of living. Through smart strategic planning and a clear understanding of asset protection, most people who file Chapter 7 or Chapter 13 bankruptcy keep their homes, personal vehicles, everyday belongings, and retirement savings.
If you are struggling with overwhelming debt, knowing how state and federal laws safeguard your property is the first step toward reclaiming control. This guide breaks down what property is exempt in bankruptcy, how Oregon bankruptcy exemptions compare to federal rules, how retirement accounts are shielded, and what practical steps you should take before filing your petition.
What Property Is Exempt in Bankruptcy?
When you file a bankruptcy petition, an "estate" is created that technically includes all your property and legal interests. However, statutory exemptions allow you to pull specific assets back out of that estate so creditors cannot touch them.
The degree of asset protection you receive depends largely on whether you file under Chapter 7 or Chapter 13:
- Chapter 7 Bankruptcy: Often called liquidation bankruptcy, Chapter 7 allows an appointed trustee to sell non-exempt assets to pay off unsecured creditors. However, if your property falls within statutory exemption limits, it cannot be sold. In fact, the vast majority of consumer Chapter 7 cases are "no-asset" filings, meaning debtors keep 100% of what they own.
- Chapter 13 Bankruptcy: Known as a wage earner's plan, Chapter 13 involves restructuring debt into a 3- to 5-year repayment plan. You keep all of your property—even non-exempt assets—provided your plan pays unsecured creditors an amount equal to the value of your non-exempt equity.
In both chapters, exemptions serve as your legal shield. Understanding which items are protected allows you to plan your filing with complete confidence.
Navigating Oregon Bankruptcy Exemptions: State vs. Federal Options

One of the most critical decisions for local filers is selecting between Oregon bankruptcy exemptions and federal bankruptcy exemptions. Oregon is a "choice state," meaning debtors can choose either the state exemption system (under Oregon Revised Statutes Chapter 18) or the federal exemptions under 11 U.S.C. § 522(d). You must select one set; you cannot combine protections from both.
Oregon State Exemptions Highlights
Oregon's state exemption set is particularly favorable for homeowners who have built up equity in their primary residence:
- Homestead Exemption (ORS 18.395): Protects up to $158,300 in home equity for single filers and up to $316,700 for married couples or joint owners. This generous allowance makes Oregon one of the most protective states for homeowners.
- Motor Vehicle (ORS 18.345): Allows filers to shield up to $10,000 of equity in a single motor vehicle per debtor. Joint filers can protect two vehicles up to $10,000 in equity each.
- Tools of the Trade: Protects up to $5,000 in tools, equipment, or implements needed for your occupation or business.
- Personal Goods: Shields household furniture, goods, apparel, and jewelry up to statutory caps.
- Wildcard Exemption: Oregon provides a modest $400 wildcard exemption for any personal property.
When Federal Exemptions Make Sense
Filers who do not own real estate often benefit more from federal exemptions. The federal system includes a substantial wildcard exemption (over $15,000 if the homestead exemption goes unused) that can safeguard bank balances, tax refunds, or secondary vehicles.
An experienced local attorney can analyze your assets to determine whether state or federal provisions deliver maximum asset protection.
Bankruptcy and Retirement Accounts: Shielding Your Future

A primary concern for people facing financial distress is whether their long-term savings will be seized. When evaluating bankruptcy and retirement accounts, the law provides exceptionally strong safeguards. Virtually all tax-qualified retirement plans are fully protected under federal and state rules.
Accounts Covered by Full Protection
- ERISA-Qualified Plans: 401(k)s, 403(b)s, defined benefit pensions, and profit-sharing accounts are completely excluded from the bankruptcy estate under federal law (11 U.S.C. § 541(c)(2)). Creditors cannot touch these funds regardless of account balance.
- Traditional and Roth IRAs: Individual Retirement Accounts are exempt under federal law up to a statutory cap of over $1.5 million per individual.
- Public Pensions: Oregon Public Employees Retirement System (PERS) accounts and other public benefits receive complete protection under state law (ORS 18.358).
Crucial Pre-Filing Warning
While funds inside a retirement account are safe, withdrawing cash before filing changes its legal status. Once pulled out and deposited into a standard bank account, those funds lose their protected ERISA status and can become reachable by creditors. Cashing out a 401(k) or IRA to pay off dischargeable credit card debt is usually an unnecessary mistake.
Protecting Your Home and Car in Bankruptcy
Your home and car are typically your most vital physical assets. Keeping them comes down to equity and payment status.
Real Estate Protections
If your home equity falls within the applicable homestead exemption limit and you are current on mortgage payments, Chapter 7 allows you to keep the home. If you are behind on payments, Chapter 13 stops foreclosure and gives you a structured window to cure arrears.
Vehicle Protections
If your vehicle equity falls under Oregon's $10,000 vehicle exemption, Chapter 7 keeps your vehicle safe. If you owe more on the car than its market value, Chapter 13 allows you to keep the car while restructuring the loan—potentially lowering your interest rate or reducing loan principal to the vehicle's fair market value.
Pre-Filing Asset Protection: Smart Steps and Costly Mistakes

Effective asset protection begins long before filing paperwork with the court.
Smart Pre-Filing Actions
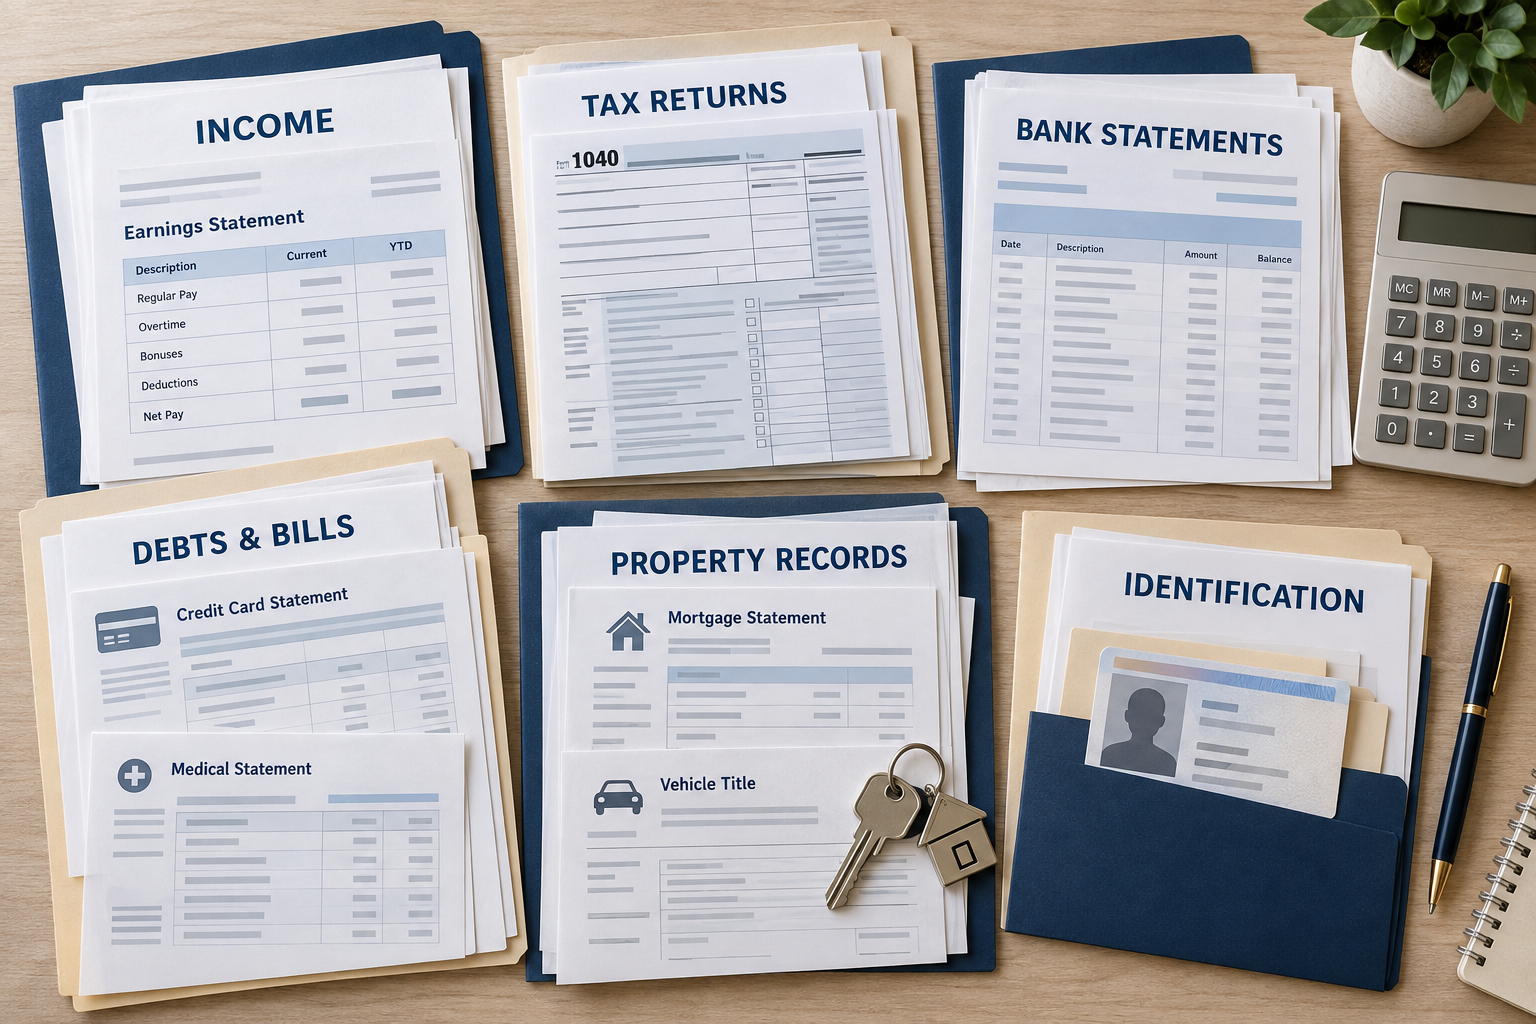
- Inventory All Property: List everything you own, including bank balances, real estate, vehicles, and household items.
- Determine Fair Market Value: Value items based on current resale value (what you could sell them for today on Craigslist or eBay), not original purchase prices.
- Ensure Full Disclosure: Transparency is vital. Attempting to hide assets or misrepresent values can lead to lost exemptions, loss of discharge, or legal penalties.
Mistakes to Avoid
- Transferring Property: Selling a car to a relative for nominal value or moving real estate titles before filing is considered a fraudulent transfer that trustees can reverse.
- Repaying Insiders First: Repaying personal loans to family members before filing creates an illegal preferential transfer that the trustee can recover.
- Incurring New Debt: Taking on major debt right before filing can trigger claims of fraud, making those balances non-dischargeable.
Take Control of Your Financial Recovery
Filing for bankruptcy does not mean starting over from zero—it means clearing unmanageable debt while preserving the essential tools, shelter, and savings required to build a stable future. By strategically utilizing Oregon bankruptcy exemptions, choosing the appropriate filing chapter, and protecting your retirement savings, you can step into a fresh financial start with confidence.
If you are navigating debt in Oregon, working with an experienced bankruptcy attorney ensures your property remains protected every step of the way. Reach out today for a confidential consultation to explore your path to lasting debt relief.
Asset Protection FAQ's
Does bankruptcy protect future income or only what I own now?
In Chapter 7 bankruptcy, only assets you own at the time of filing are typically included in the case. However, in Chapter 13, your future disposable income is part of the repayment plan. Certain future income streams, like tax refunds or inheritances received within 180 days of filing, may be considered part of your bankruptcy estate in either chapter. Timing your filing carefully is essential to avoid losing unexpected windfalls.
Are personal injury settlements protected in bankruptcy?
It depends. Personal injury settlements may be partially or fully exempt depending on the type of damages and the exemption laws in your state. For example, compensation for lost wages or medical expenses may be protected, while punitive damages often are not. Oregon and federal exemptions differ on this, so it's crucial to work with a bankruptcy attorney to determine what portion of a settlement can be retained.
What happens to jointly owned property if only one spouse files for bankruptcy?
If only one spouse files, jointly owned property may still be at risk depending on how it's titled and your state’s laws. In Oregon, which is not a community property state, the non-filing spouse’s interest is generally protected. However, the trustee can still reach the filer’s portion of any jointly owned non-exempt asset. This makes it especially important to understand tenancy laws and file strategically as a household.

Share On: